
Decisions! Keep it and rent it or sell it and invest?
The Fate of an East River Co-op 1BR
I ran into my friend, Cedric, the other day on East Broadway.
We were both walking west toward the Manny Cantor Center, headed in roughly the same direction before eventually splitting off at Clinton Street — him for an ice cream at Julie Jeans, and me for a visit to Seward Park Co-op’s management office.
As we walked, I asked if he’d ever eaten at Dolce Momento. “No,” he replied, admitting that he’d never passed by when it was open. We then pivoted to a different topic: a situation he was facing for which he sought my professional opinion.
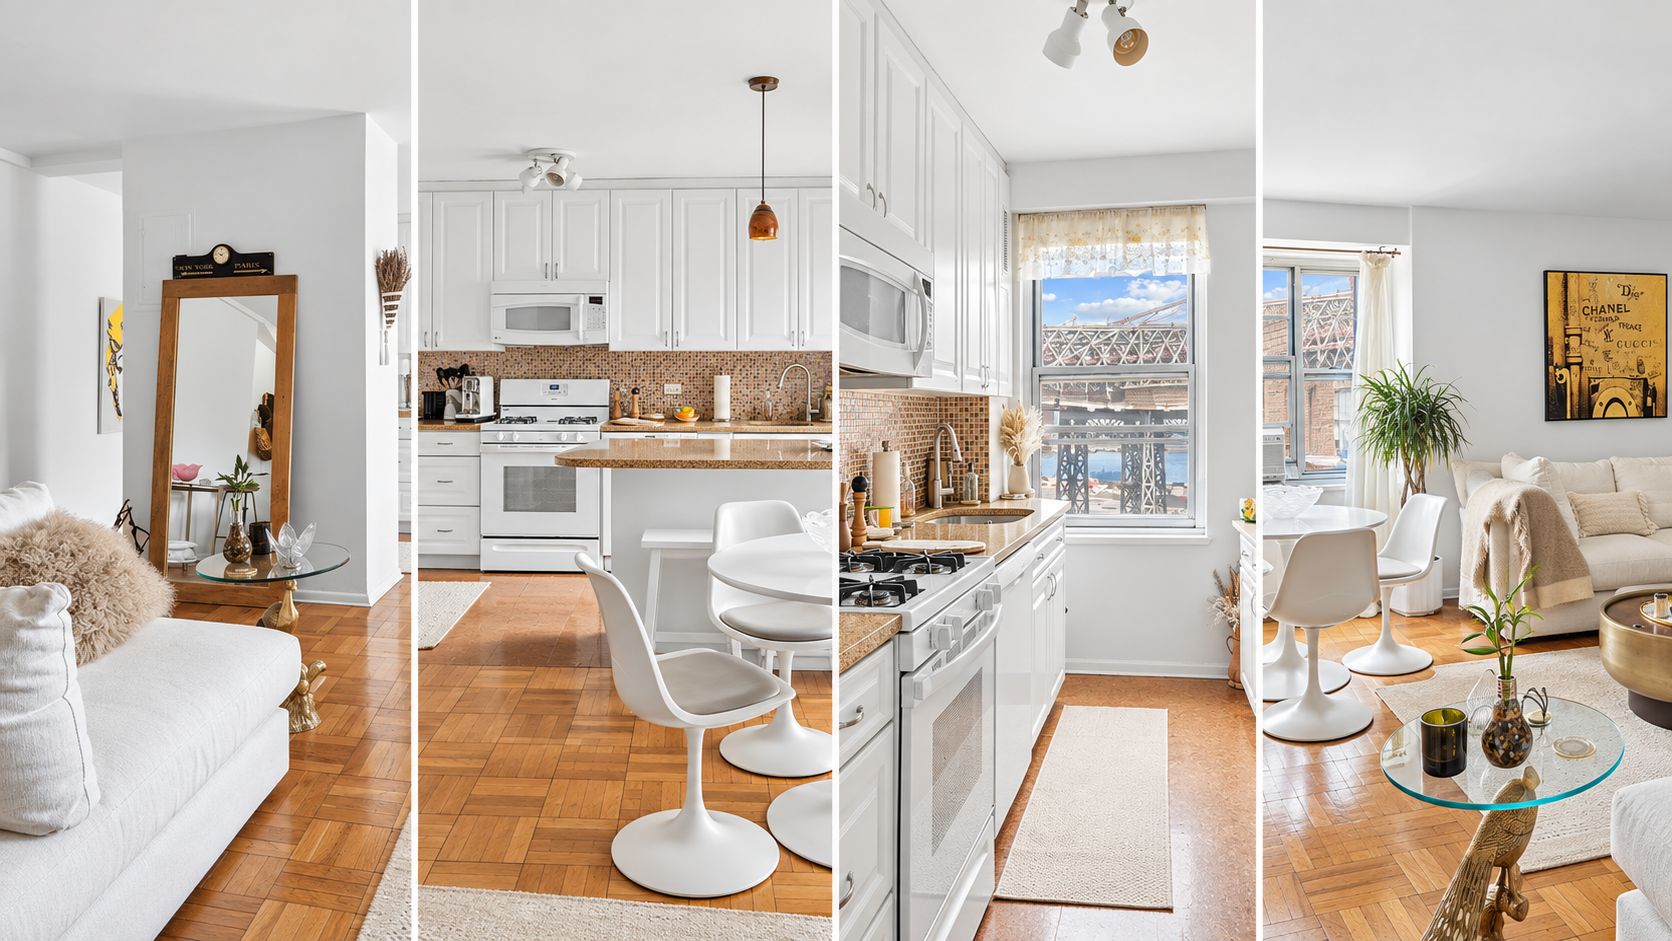
His parents had lived for many years in a well-maintained ninth-floor one-bedroom apartment in East River Co-op. They’d recently relocated to Wilmington, North Carolina, where his sister had taken up residence.
The milder winters, relaxed pace, salty grits and proximity to scenic Masonboro Island fit closely with the retirement his parents had envisioned. Just as importantly, they had an adult child and two grandchildren nearby.
But that left Cedric with a predicament back in New York.
His parents had an apartment in excellent condition that the family no longer needed. Cedric also had a potential tenant interested in renting it.
We approached the corner, ruing the lack of time to discuss the matter over a pint at Eastwood. So, he asked:
“What would you do? Would you hold it and rent it, knowing you could net about $150 a month, or would you sell it? What’s the better choice over a five-year horizon?”
I told him I’d do a back-of-the-napkin analysis, and here it is, for Cedric — not his real name — and you, dear reader.
First, What Is the Apartment Worth?
I started with the available data for one-bedroom, one-bath apartments across East River Co-op, going back through 2024.
The data set included closed transactions, listings that came off the market without a recorded sale, and apartments currently being offered for sale or in contract as of October 2026.
Across that period, there were 47 recorded closed one-bedroom transactions, along with another 15 one-bedroom apartments for sale and an additional nine one-bedroom apartments in contract. There were also 11 listings that had come off the market without a recorded closing.
Across the recorded sales, the average price was approximately $611,500, with a median of $605,000.
But averages across an entire complex are only so revealing, particularly in buildings that rise 20 stories or more. Cedric’s parents’ apartment is on the ninth floor, placing it roughly in the middle of the building. I narrowed the analysis to apartments on comparable middle floors, where pricing would provide a more relevant benchmark.
Within this segment, I noted 11 recorded sales. They averaged approximately $611,800, with a median of $600,000 and prices ranging from $590,000 to $675,000.
Then I narrowed it again, looking at five sales from a single floor within that range. Those transactions ranged from $600,000 to $675,000, with an average sale price of $622,000 and a median of $610,000.
Condition matters. Exposure matters. Layout matters. Renovation quality matters. There is no spreadsheet that can tell you precisely what an individual apartment will sell for, or when a prospective buyer will appear and say, “That apartment just feels and looks right.”
Scenario 1: Sell and Reinvest
For our back-of-the-napkin exercise with Cedric, let’s assume a list price of $622,000, with a gross sale price that meets the ask, i.e., $622,000.
Let’s also assume 5% in brokerage fees (2.5% each for the listing agent and buyer’s agent) and a 5% flip tax, which East River Co-op imposes on second-generation sellers (and later).
That's $62,200 off the top, leaving estimated net proceeds of $559,800.
There are other potential closing costs, of course, and this doesn't account for any outstanding mortgage on the existing apartment. But again, this wasn't intended to be a closing statement.
We were trying to answer a larger question: What could you do with the money instead?
For the sake of comparison, let's assume the $559,800 becomes the purchase price of another property.
Rather than buying it for cash, let's assume a 20% down payment of $111,960, with the remaining $447,840 financed through a 30-year fixed mortgage at an assumed rate of 7.28%.
That produces a principal-and-interest payment of approximately $3,064 per month, before maintenance, taxes, insurance or other carrying costs.
Over five years, that's 60 mortgage payments totaling approximately $183,851.
Of that, approximately $25,044 would go toward paying down principal, while approximately $158,807 would go toward interest. At the end of five years, the mortgage balance would be approximately $422,796.
But there's another important part of the equation.
If only $111,960 of the original $559,800 in sale proceeds is used for the down payment, that leaves approximately $447,840 available to invest elsewhere.
I didn't assign a hypothetical return to that money. Cedric could put it in equities. Bonds. Another real estate investment. A high-yield account. Something else entirely.
The point is simply that the money doesn't disappear because he financed the replacement property. It remains an asset available for another use.
Scenario 2: Keep the Apartment and Rent It
Now let's go back to the other side of the equation. Cedric has a prospective tenant lined up.
Based on the rent he could collect and the costs associated with keeping the apartment, he estimated that he would net approximately $150 per month. (That’s modest, of course, but it’s profit.)
That's also $1,800 per year, or $9,000 over five years.
And, of course, his family would still own the apartment at the end of those five years, with the possibility of a more favorable market for sellers and lower interest rates (one can only hope).
Which Scenario Is Better for Cedric?
It’s here that the back-of-the-napkin analysis stops, and real life starts.
There are too many variables, exigencies and circumstances shaping a decision like this to give a direct or definitive answer.
What happens to the value of the East River apartment over the next five years? What happens to the value of the replacement property? What return could the remaining $447,840 generate if invested? What happens to mortgage rates? What are the carrying costs of each property? Does the tenant stay? Does the rent increase? How much does the owner value liquidity versus continuing to own the apartment?
Change any of those inputs and Cedric’s outcome also changes.
But that's also why I found the exercise useful. The question started with Cedric asking: “Should I sell the apartment or collect an extra $150 a month?”
Once we put some numbers behind it, the question became broader. If Cedric sells, what do he and his family actually walk away with? If they reinvest some of it in another property, what does the financing look like? How much equity will they build? Will having a rental tenant be more or less of a headache than selling the apartment, or even just carrying it?
Also, very importantly: What could they do with the capital that is no longer tied up in the apartment?
Sometimes the value of a back-of-the-napkin analysis isn't that it gives you the answer. It's that it helps you figure out the right question … which is precisely what Cedric asked, and then pondered over a pint of Chocolate Chocolate Shower.